Applying for jewellery EMI without knowing the approval-to-delivery sequence means you either overpay in card interest or wait weeks longer than necessary for a handcrafted piece. Set up the right emi jewellery payment plan before you order, and the whole cycle — approval, craft time, hallmark verification, delivery — runs on a schedule you control instead of one the lender or the workshop controls for you.
- An emi jewellery payment plan works fastest when KYC and address proof are ready before you select a piece, not after.
- No-cost EMI on cards typically runs in 3, 6, 9 or 12 month tenures — check your bank's standard cycle before committing.
- Bespoke and bridal commissions at Auram Jewellery need craft time built into the EMI schedule, so confirm timelines before the first installment.
- BIS hallmarking (HUID) and IGI certification should be verified before final payment clears, not after delivery.
- 3% GST applies on jewellery value under current Indian tax rules — factor this into the EMI principal, not as a surprise at checkout.
Why this matters
Most jewellery EMI complaints in 2026 trace back to two gaps: the buyer didn't confirm the craft timeline before the EMI clock started, or the buyer didn't verify hallmarking before the final installment cleared. Both are avoidable with a sequence, not a checklist you skim once.
A bespoke gold or diamond piece isn't a same-day dispatch item. When you're financing a purchase through the gold rate to purchase workflow, the payment schedule and the karigar's production schedule need to run in parallel, not in sequence — otherwise you're paying installments on a ring that hasn't started being made.
Before you start
- KYC documents ready: PAN card, address proof, and (for NBFC-financed EMI) income proof — banks and finance partners reject incomplete applications outright, which restarts your approval clock.
- Know your card's EMI cycle: Indian banks generally convert purchases to no-cost EMI in 3, 6, 9 or 12 month tenures on credit cards; confirm which tenures your specific card supports before you lock a piece.
- The gotcha: if you're financing a bespoke or bridal commission, the EMI tenure starts from the transaction date, not the delivery date. A 6-8 week craft timeline on a 3-month EMI tenure means you're paying installments on jewellery still on the karigar's bench — build in a longer tenure or a milestone-payment structure instead.
Choose your EMI jewellery payment plan
- Shortlist the piece — ready-to-ship or bespoke — and note its listed value including making charges.
- Check whether the checkout offers card EMI (bank-issued, no-cost on most cards) or a finance partner EMI (NBFC-backed, may carry processing fees).
- Confirm the GST treatment: jewellery in India carries 3% GST on the metal and stone value, applied before your EMI principal is calculated.
- Select tenure based on the craft timeline, not just the smallest monthly figure — a shorter tenure on a commission piece front-loads payments before delivery.
Expected result: you have a fixed EMI principal, a confirmed tenure, and a payment schedule that matches — or exceeds — the production timeline.
Get EMI approval
- Submit KYC documents through your bank's app or the finance partner's portal at checkout.
- Wait for the credit check — approval timing depends entirely on your bank or NBFC, not the jeweller.
- Once approved, you'll receive a confirmation with EMI amount, tenure, and the first debit date.
- Cross-check that the EMI confirmation matches the order value quoted by Auram Jewellery — mismatches at this stage are the single most common cause of billing disputes later.
Expected result: an approval notification from your lender showing the exact EMI schedule, which you should save alongside your order confirmation.
Confirm your order and craft timeline
- For ready pieces, confirm dispatch timing directly with the order team.
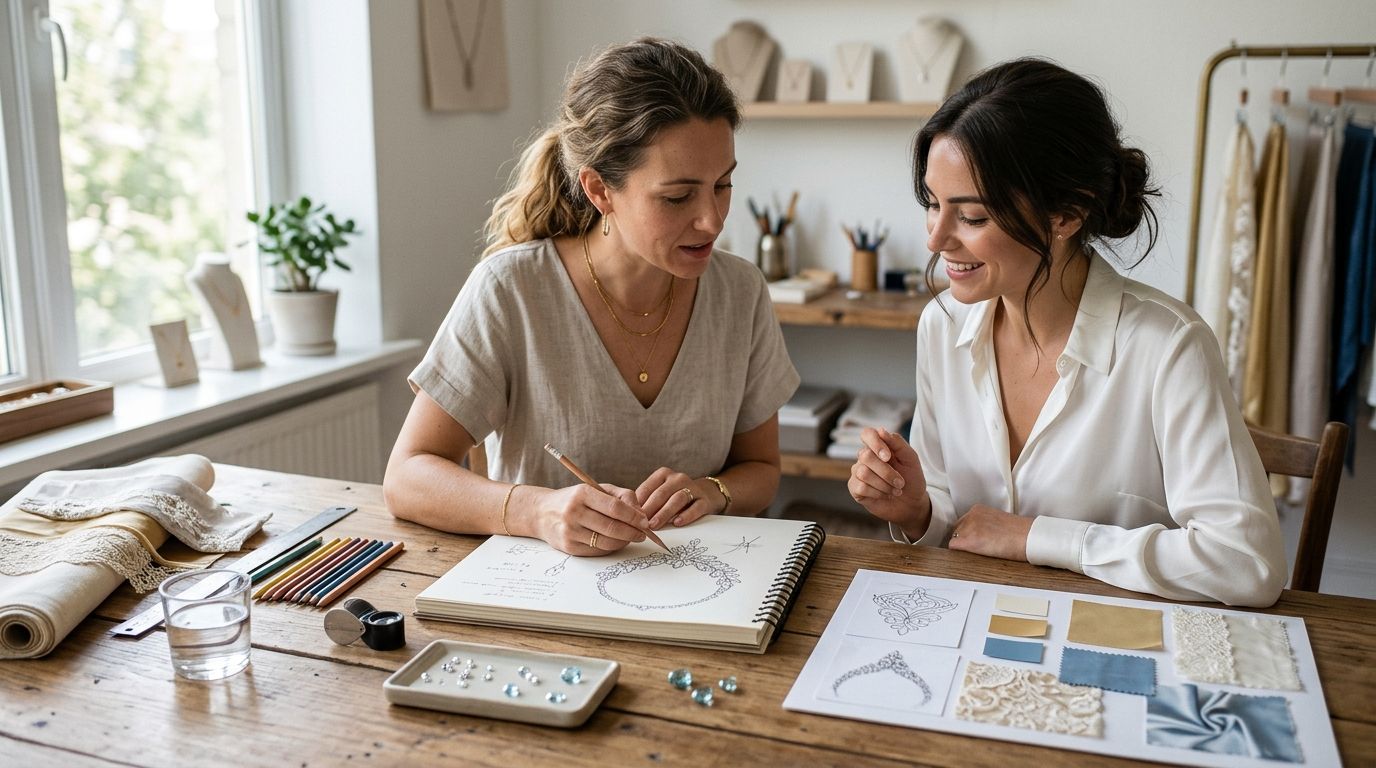
- For bespoke commissions, book a video consultation for bespoke jewellery to lock design details, gold purity (22KT/916 for traditional bridal pieces), and stone selection before the karigar starts work.
- Ask for a written craft timeline — third-generation karigars working by hand need real production time, and that timeline should be logged against your EMI schedule.
- Verify BIS hallmarking (HUID number) and, for diamond pieces, the IGI certificate number are part of the delivery package before the final EMI installment is due.
Expected result: a documented production timeline that overlaps cleanly with your EMI tenure, with no installment due before the piece is confirmed in production.
Paying by full advance instead of EMI
Some buyers skip EMI entirely and pay in full to lock the gold rate on the transaction date — worth doing when gold rates are rising and you want price certainty rather than a spread-out schedule. The trade-off: no monthly flexibility, and the full principal plus 3% GST is due upfront instead of staged. Use EMI when cash flow matters more than rate timing; pay in full when locking today's gold rate matters more than monthly flexibility.
Payment method comparison
| Method | How it works | Best for | Verdict |
|---|---|---|---|
| Card no-cost EMI | Bank converts the purchase to a 3/6/9/12-month EMI on your existing credit card | Buyers who want zero processing fees and already have card limit available | Buy |
| NBFC finance partner EMI | Third-party lender finances the purchase, may include processing fees | Buyers without sufficient card limit for higher-value bridal sets | Consider |
| Full advance payment | Entire amount plus GST paid upfront at order confirmation | Buyers prioritising today's gold rate over monthly flexibility | Buy |
| Milestone/staged payment | Payment split across design confirmation, production start, and delivery | Bespoke commissions with longer craft timelines | Buy |
“A shorter EMI tenure on a bespoke commission front-loads payments before the piece exists — match your tenure to the karigar's timeline, not the other way around.”
Troubleshooting
- EMI application rejected: usually a credit limit or income-documentation gap on the lender's side — reapply with updated income proof or switch to full advance payment.
- Approval delayed past your planned order date: normal for NBFC-financed EMI during high-volume wedding season; build in a buffer week when ordering bridal sets against a fixed date.
- Gold rate shifted between approval and delivery: the EMI principal is fixed at the transaction date regardless of later rate movement — this protects you if rates rise after approval.
- Hallmarking or IGI certificate missing at delivery: hold your final installment confirmation until you've personally verified the HUID number and the IGI certificate number against the physical piece.
- Delivery address mismatch: update address details with both the courier and your finance partner before the first EMI debit — a mismatch here delays dispatch even after payment clears.
Start your EMI jewellery payment plan
Browse handcrafted gold, diamond and bridal collections before you apply for EMI.
Customize your workflow
If you're ordering a bridal set against a fixed wedding date in 2026, move the EMI approval step earlier than usual — confirm financing before you finalise the design, not after. If you're buying a gift piece with a shorter production window, full advance payment or a 3-month EMI cycle is simpler than staged milestone payments.
Before you commit either way, read the BIS hallmarking verification guide so the purity check at delivery takes two minutes instead of two days. Keep your order confirmation, EMI approval notice, hallmark HUID and IGI certificate number in one place before the final installment is due — that document set is what protects you if a dispute comes up after delivery.
FAQ
What is an emi jewellery payment plan?
An emi jewellery payment plan splits the cost of gold, diamond or silver jewellery into fixed monthly installments through your bank's card EMI facility or a finance partner. Tenures usually run 3, 6, 9 or 12 months, and the principal is fixed at the transaction date regardless of later gold rate movement.
Is no-cost EMI actually free on jewellery purchases?
No-cost EMI on most Indian bank credit cards carries no separate interest charge to the buyer. NBFC finance partner EMI can carry a processing fee, so compare the total payable across both routes before choosing.
How long does EMI approval take for a jewellery purchase in 2026?
Approval depends on your bank or NBFC credit check, not the jeweller, and ranges from same-day to a few business days. Apply before finalising a bespoke commission so the craft timeline is not delayed waiting on financing.
Can I use EMI for a bespoke or bridal commission?
Yes, but match the EMI tenure to the craft timeline confirmed during your design consultation rather than starting it before production begins. A tenure shorter than the production window means installments fall due before the piece is finished.
Does GST apply on top of the EMI principal?
Jewellery in India carries 3% GST on the gold and stone value, and that is included in the EMI principal calculated at checkout. It is not added separately at a later installment.
What happens if the gold rate changes after I am approved for EMI?
Your EMI principal is fixed at the transaction date, so later gold rate increases or decreases do not change your installment amount. That rate lock is one practical advantage of EMI over delaying a full payment.
Should I verify hallmarking before or after my final EMI installment?
Verify the BIS HUID number and, for diamond pieces, the IGI certificate number at delivery and before your final installment clears. This gives you documented proof of purity while you still have an outstanding payment as leverage.
What if my EMI application gets rejected?
Rejections usually come from insufficient credit limit or incomplete income documentation on the lender's side. Reapply with updated documents or switch to full advance payment to keep your order timeline on track.
One last thing
The detail buyers skip most often in 2026: matching the EMI tenure to the karigar's production calendar, not the calendar month you happened to place the order in. A 3-month tenure on a piece with a 6-8 week bespoke timeline means two installments fall due before the ring exists — ask for the written craft timeline before you pick a tenure, every time.